By The Searchlight Editorial Team / August 13, 2026
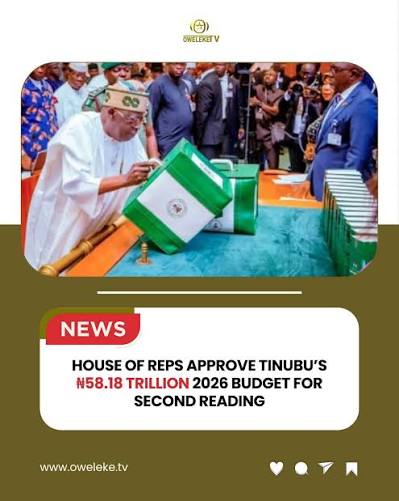
In this second part of The Searchlight findings on the 2026 Nigerian federal budget include the following findings:
- Scale of opacity: The ₦68.32 trillion Appropriation Act (signed April 2026) contains widespread mismatched allocations, missing project locations, overlapping/duplicated spending (at least ₦210 billion identified), and off-mandate projects inserted mainly as constituency/zonal interventions.
- Palace projects: ₦22.15 billion allocated for 106 traditional rulers’ palace construction/renovation/furnishing. 11 projects (≈₦5.85 billion) have no identified locations. None of the ~45 implementing MDAs have a statutory mandate for royal residences; funds routed through agricultural colleges, research institutes and health bodies (including NICRAT for cancer research).
- Broader ceremonial/religious spending: ~78 MDAs collectively earmarked nearly ₦400 billion for community halls, market squares, civic centres, mosques, churches and palaces. Separate religious lines ≈₦8 billion (₦1.91 billion churches, ₦6.14 billion mosques).
- Federal Cooperative College, Oji River: Massive capital envelope (analyses cite hundreds of billions to over ₦1 trillion across thousands of line items/2,791 projects). Used as a major conduit for nationwide solar street lights, transformers, electrification, vehicles, tractors, tricycles, motorcycles, boats and empowerment items—entirely outside its cooperative-education mandate.
- Other mandate hijacking examples: National Institute for Cancer Research and Treatment (NICRAT) given palace renovation funds; National Commission for Almajiri and Out-of-School Children Education assigned road projects (including a reported ₦1.4 billion Ogun road); similar diversions in NBRRI, National Productivity Centre, research institutes and others.
- Political-campaign linkage claims: Opposition figures and civic groups have alleged the opacity and Service-Wide Vote surge (to ₦12.8 trillion) could fund APC 2027 machinery. Separate media reports (The Searchlight inclusive) alleged ₦800 billion in FAAC deductions by APC governors for Tinubu’s re-election vehicles (Renewed Hope entities); SERAP has sued INEC for investigation.
- Overall pattern: Long-standing bipartisan practice of inserting constituency projects into convenient MDAs, has intensified in scale. It creates opportunities for waste, ghost projects and reduced accountability.
Clear Mandate Violations in the 2026 Nigerian Federal Budget
There are documented cases where projects were assigned to Ministries, Departments and Agencies (MDAs) that have no statutory or legal mandate to execute them. These include:
- Federal Cooperative College, Oji River (Enugu State)
The institution’s core mandate is academic and professional training in cooperative education and management.
The violation of the mandate is the allocation of hundreds of billions of naira (analyses cite up to ₦1+ trillion across thousands of line items) for nationwide solar street lights, transformers, rural electrification, roads, drainage, markets, vehicles, tractors, tricycles, motorcycles, fishing boats, ambulances, dialysis centres, empowerment schemes and palace-related works, none of which fall under cooperative education. - National Institute for Cancer Research and Treatment (NICRAT)
It’s core mandate Cancer research, treatment and related health functions.
It is amazing that ₦200 million was allocated to the Institute for renovating district heads’ palaces in Gudu/Tangaza, in Sokoto State. - Nigerian Building and Road Research Institute (NBRRI)
The core mandate is research on building materials, construction technology and roads. However, ₦3.92–4 billion was inserted for traditional rulers’ palace construction/renovation, pavilions, solar power installations, village halls, international markets, multipurpose halls and mosque remodelling across multiple states. - Federal Cooperative College, Ibadan
The core mandate is cooperative education and training yet
multi-billion-naira projects (including ₦2.661 billion) for renovation of community halls and palaces in Lagos, Ekiti South and Ondo South. - National Productivity Centre
Core mandate: Promoting productivity and competitiveness in the economy.
Violations: Construction/renovation of Emirs’ and Obas’ palaces, support for musicians, abattoirs and other unrelated infrastructure. - National Commission for Almajiri and Out-of-School Children Education (NCAOOSCE)
Core mandate: Reform of Almajiri system and reduction of out-of-school children through education and skills.
Violations: Road construction projects (including a reported ₦1.4 billion road in Ogun State) plus ambulances, medical equipment and solar installations outside its educational focus. (The Commission itself stated these were National Assembly constituency insertions.) - Broader pattern across ~45–78 MDAs
Agricultural colleges, research institutes, health facilities, river basin authorities and other specialized bodies were assigned traditional rulers’ palace projects (total ₦22.15 billion for 106 palaces), church/mosque works (≈₦8 billion) and community infrastructure with no connection to their legal mandates. Eleven palace projects (≈₦5.85 billion) have no identified locations at all.
These assignments bypass the agencies’ enabling laws, dilute focus on their core functions, and reduce effective oversight and accountability.
Legal Implications of the Documented Issues in Nigeria’s 2026 Appropriation Act
The documented practices of assigning projects to MDAs outside their statutory mandates, inserting large volumes of constituency-style projects under mismatched headings, and creating opacity through vague or location-less allocations, raise several legal questions under the 1999 Constitution (as amended), the Fiscal Responsibility Act 2007, the Public Procurement Act 2007, enabling laws of individual MDAs, and anti-corruption statutes. Below is a structured analysis based on the applicable legal framework.
1. Constitutional Framework (Sections 80–84)
- Public funds may only be withdrawn from the Consolidated Revenue Fund pursuant to an Appropriation Act passed by the National Assembly and assented to by the President.
- Implication: Mere insertion of projects (even off-mandate ones) into a duly passed and signed Appropriation Act does not, by itself, render the allocation unconstitutional. The Act provides the legal authority to spend. However, this does not immunize subsequent implementation from other laws. Courts have not issued a definitive Supreme Court ruling clarifying the precise limits of the National Assembly’s power to insert entirely new capital projects without executive initiation, leaving a zone of legal uncertainty that civil society groups (including BudgIT) have repeatedly flagged for judicial clarification.
2. Mandate Violations and Ultra Vires Actions
- Every MDA operates under an enabling statute or legal instrument that defines its functions. Assigning palace construction to a cancer research institute, nationwide electrification to a cooperative college, or road works to an Almajiri education commission falls outside those statutory purposes.
- Implication: While the Appropriation Act may authorize the spending, an MDA that proceeds to award and execute contracts far outside its mandate risks acting ultra vires. Accounting officers (Permanent Secretaries or equivalent) bear personal responsibility under the Public Procurement Act. Such actions can form the basis for:
- Administrative sanctions
- Queries by the Auditor-General
- Civil or criminal liability if funds are misapplied
- Challenges to the validity of contracts awarded
3. Fiscal Responsibility Act 2007
- Requires budgets to be realistic, consistent with economic objectives, transparent, and prioritized according to contribution to socio-economic development (Sections 18–19 and related provisions).
- Mandates prudent management and accountability in fiscal operations.
- Implication: Large-scale off-mandate insertions, overlapping allocations, and projects with no identified locations undermine the Act’s transparency and prioritization requirements. Persistent patterns can attract civil society litigation seeking enforcement of disclosure and audit obligations, though direct criminal penalties under the Act itself are limited.
4. Public Procurement Act 2007
- Requires open, competitive, transparent processes that deliver value for money. Accounting officers are personally liable for breaches.
- Contracts must have budgetary provision, cash backing, and proper warrants.
- Implication: When an MDA without technical capacity or mandate is forced to procure complex infrastructure (roads, solar grids, palace works), the risk of non-competitive awards, inflated costs, poor supervision, and procurement irregularities rises sharply. Recent Treasury circulars emphasize that awarding contracts without proper cash backing or warrants can constitute offences under the ICPC Act. The Bureau of Public Procurement can recommend sanctions, debarment of contractors, or disciplinary action against officers.
5. Anti-Corruption Laws (EFCC Act, ICPC Act, Criminal Code/Penal Code)
- Misappropriation, diversion, or fraudulent conversion of public funds, as well as abuse of office, are criminal offences.
- Implication: Opacity and mandate mismatch create an environment conducive to graft, but criminal liability requires proof of actual diversion, personal enrichment, or corrupt intent—not merely the existence of an off-mandate line item in the Appropriation Act. No publicly available forensic evidence has yet established such diversion of the specific 2026 palace, cancer-research, or Oji River lines into private or campaign accounts. Allegations of FAAC-related campaign funding are the subject of ongoing SERAP litigation against INEC and remain unproven in court.
6. Electoral and Campaign Finance Dimensions
- The Electoral Act regulates political party and candidate financing, including limits on donations and prohibitions on the use of public funds for campaigns.
- Implication: If any portion of appropriated funds were later diverted to APC or individual campaign vehicles, that would constitute a separate and serious offence under the Electoral Act and anti-corruption laws. Current public allegations (e.g., the ₦800 billion FAAC claims) have prompted litigation seeking investigation but have not produced judicial findings of guilt or forensic confirmation linking the contested 2026 budget lines.
7. Practical and Institutional Consequences
- Auditor-General and Public Accounts Committees: Can issue adverse reports and recommend recoveries or prosecutions.
- Judicial review: Citizens or NGOs can seek orders compelling disclosure, audits, or restraint on ultra vires expenditure.
- Presidential and legislative responsibility: By assenting to a budget containing these features, the President and National Assembly share political and institutional accountability, even if individual criminal liability is not automatically engaged.
- Contract risk: Contractors executing clearly off-mandate works face heightened risk of payment disputes, contract nullification, or future debarment if irregularities are established.
Conclusion
The Appropriation Act itself provides legal cover for the allocation of the funds. However, the systematic assignment of projects outside MDAs’ statutory mandates, combined with opacity, creates significant legal vulnerabilities at the implementation stage under the Fiscal Responsibility Act, Public Procurement Act, and anti-corruption statutes. These practices weaken accountability, increase the risk of waste and abuse, and leave open pathways for civil, administrative, and (if evidence of diversion emerges) criminal consequences. Definitive resolution of the scope of legislative insertion powers and stronger enforcement of mandate fidelity would require either legislative reform or authoritative judicial interpretation.


Leave a comment